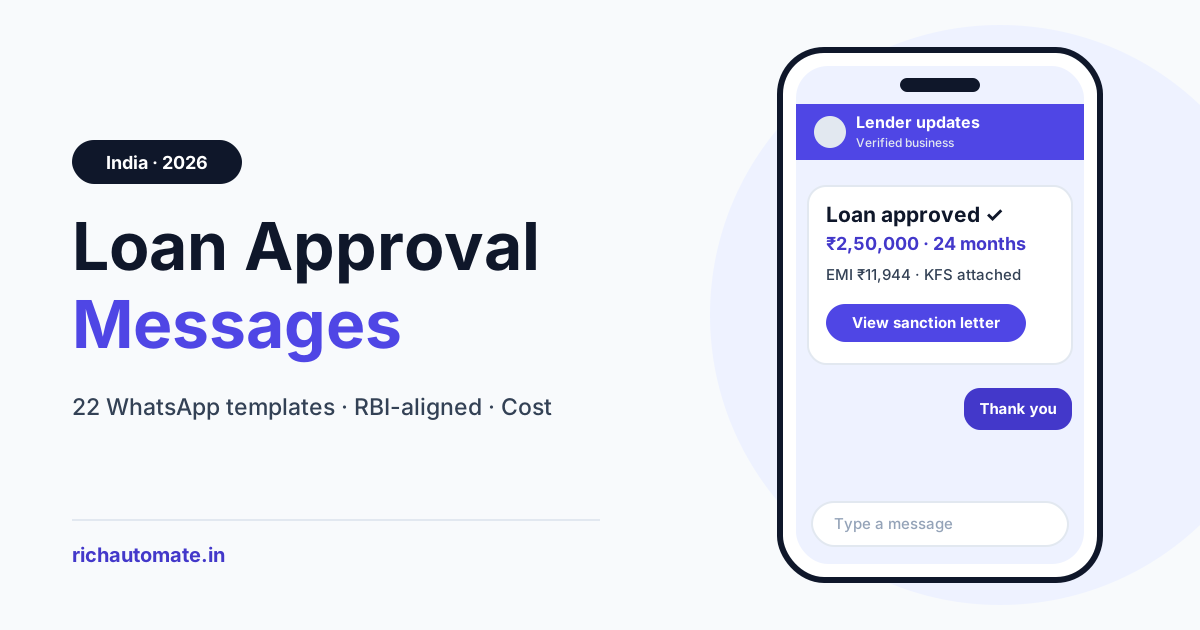
A loan approval message is a short notice sent when a loan is sanctioned. It states the approved amount, the interest rate and APR, the tenure, the EMI and the next step (sign the agreement, set up the e-mandate or complete KYC), and it links the Key Fact Statement (KFS). Example: “Dear Customer, your personal loan of ₹2,50,000 from Sample Finance Ltd is approved at 13.5% p.a. (APR 14.9%) for 24 months. EMI: ₹11,944 from 5 Nov 2026. Please review your Key Fact Statement, then sign the agreement and set up your e-mandate.” If you send it on WhatsApp outside the 24-hour window, it must be a pre-approved Utility template with {{variables}}. That costs about ₹0.115 per delivered message at Meta’s India utility rate (BSP-reported; Meta revises rates, so confirm the live rate card).
What a loan approval message must contain
A loan approval message should state the amount, the rate, the tenure, the EMI and the next step — and link the Key Fact Statement. Under the RBI digital lending rules for WhatsApp, the KFS must reach the borrower before they are bound. Acceptance is a separate step.
Always include
- Borrower first name and loan type
- Approved amount, interest rate and all-in APR
- Tenure, EMI and first-EMI date
- Processing fee
- KFS or sanction-letter link
- Next step and offer validity
- Regulated lender name (plus the LSP, if one is involved)
- Grievance contact
Never include
- OTPs, passwords or PINs
- Full account, Aadhaar or PAN numbers. Mask them instead (“account ending 4821”)
- Pressure language such as “accept now or lose it”
The loan lifecycle message map
| Stage | Trigger | Template category | Key variables |
|---|---|---|---|
| Application received | Application created in LOS | Utility | Name, application ID, lender |
| Documents pending | Missing documents flagged | Utility | Document list, upload link |
| Under review | File enters credit assessment | Utility | Application ID, update date |
| Approved / sanctioned | Final credit decision | Utility | Amount, rate, APR, tenure, EMI, KFS link |
| Agreement + e-mandate | Agreement generated | Utility | E-sign link, mandate link |
| Disbursed | Disbursal posted in LMS | Utility | Amount, account ending, first EMI |
| EMI reminder | Days before due date | Utility | EMI, due date, pay link |
| EMI received | Payment posted | Utility | Amount, date, next EMI |
| EMI bounced | NACH return or failed debit | Utility | Amount, reason, charge, pay link |
| Closed / NOC | Final payment posted | Utility | Closure date, NOC |
| Rejected | Credit decline recorded | Utility | Reason category, grievance contact |
| Top-up offer | Campaign list | Marketing | Offer amount, validity |
22 copy-paste loan message templates
Written for NBFCs, banks, fintech LSPs and DSAs. Each key lists the numbered variables in order.
Loan approved / sanctioned
1. Personal loan
Dear {{1}}, your personal loan of {{2}} from {{3}} is approved at {{4}} p.a. (APR {{5}}) for {{6}} months. EMI: {{7}} from {{8}}. Processing fee: {{9}}. Review your Key Fact Statement: {{10}}. Next step: sign the agreement and set up your e-mandate by {{11}}, as per your sanction terms.
Key: name, amount, lender, rate, APR, tenure, EMI, first EMI date, fee, KFS link, valid-until date.
2. Business loan
Hello {{1}}, the business loan for {{2}} is sanctioned by {{3}} for {{4}} at {{5}} p.a. (APR {{6}}), EMI {{7}}. Sanction letter and KFS attached. Please sign by {{8}}. Grievance officer: {{9}}. Thank you.
Key: name, business, lender, amount, rate, APR, EMI, sign-by date, grievance contact; PDF header.
3. Home loan
Dear {{1}}, home loan {{2}} is sanctioned by {{3}} for {{4}} at {{5}} p.a. (APR {{6}}) over {{7}} years, indicative EMI {{8}}. Sanction letter and KFS attached. Offer valid until {{9}}; disbursement follows property and legal checks.
Key: name, application ID, lender, amount, rate, APR, tenure, EMI, validity date.
4. Gold loan
Dear {{1}}, your gold loan of {{2}} against {{3}} g of gold is approved by {{4}} at {{5}} p.a. (APR {{6}}) for {{7}} months. KFS and pledge terms: {{8}}. Keep your pledge receipt safe.
Key: name, amount, gold weight, lender, rate, APR, tenure, KFS link.
5. Two-wheeler loan
Hi {{1}}, your loan for the {{2}} is approved by {{3}} for {{4}} at {{5}} p.a. (APR {{6}}), EMI {{7}} for {{8}} months. KFS: {{9}}. Complete your e-mandate so the dealer can release the vehicle.
Key: name, model, lender, amount, rate, APR, EMI, tenure, KFS link.
6. Education loan
Dear {{1}}, the education loan for {{2}} is sanctioned by {{3}} for {{4}}. Rate {{5}} p.a. (APR {{6}}); repayment starts {{7}}. Sanction letter and KFS attached. Co-borrower e-sign due by {{8}}. Thank you.
Key: name, course, lender, amount, rate, APR, repayment start, e-sign date.
Conditional approval / documents pending
7. Conditional approval
Dear {{1}}, application {{2}} with {{3}} is conditionally approved for up to {{4}}. Final sanction needs {{5}}, uploaded here: {{6}}. Final rate, APR and EMI will follow in your KFS.
Key: name, application ID, lender, indicative amount, pending items, upload link.
8. Documents pending
Hello {{1}}, to continue application {{2}} with {{3}} we need {{4}}. Upload securely here: {{5}}. Never share OTPs or passwords on this chat.
Key: name, application ID, lender, document list, upload link.
E-sign and e-mandate pending
9. Agreement ready to sign
Dear {{1}}, loan {{2}} of {{3}} with {{4}} is ready to sign. Read the Key Fact Statement and sign here: {{5}}. The link works until {{6}}; we can resend it.
Key: name, loan ID, amount, lender, e-sign link, expiry date.
10. E-mandate pending
Hi {{1}}, one step left on loan {{2}} with {{3}}: set up the e-mandate for your EMI of {{4}} from the account ending {{5}} here: {{6}}. Disbursement follows mandate registration.
Key: name, loan ID, lender, EMI, last four digits, mandate link.
Loan disbursed
11. Disbursed to borrower
Dear {{1}}, loan {{2}} from {{3}} is disbursed. Amount {{4}} was credited to the account ending {{5}} on {{6}}. First EMI {{7}} on {{8}}. Grievance officer: {{9}}. Thank you.
Key: name, loan ID, lender, net amount, last four digits, date, EMI, first EMI date, grievance contact.
12. Disbursed to dealer or seller
Hello {{1}}, your lender {{2}} has paid {{3}} for loan {{4}} directly to {{5}} on {{6}}. First EMI of {{7}} is due on {{8}} via e-mandate.
Key: name, lender, amount, loan ID, dealer or seller, date, EMI, due date.
EMI due reminder
UPI AutoPay pre-debit notices must arrive at least 24 hours before the debit. See our compliant WhatsApp loan recovery sequence for the full cadence.
13. EMI due in a few days
Dear {{1}}, reminder from {{2}}: your EMI of {{3}} for loan ending {{4}} is due on {{5}} and will be debited via e-mandate. To pay another way: {{6}}. Ignore this if already paid.
Key: name, lender, EMI, last four digits, due date, pay link.
14. EMI due today
Hi {{1}}, your EMI of {{2}} for loan ending {{3}} with {{4}} is due today. Please keep the balance ready for your e-mandate. Pay online: {{5}}. Need more time? Reply TALK.
Key: name, EMI, last four digits, lender, pay link.
EMI received
15. EMI received
Dear {{1}}, your EMI of {{2}} for loan ending {{3}} with {{4}} was received on {{5}}. Next EMI {{6}} is due on {{7}}. Thank you for paying on time.
Key: name, amount, last four digits, lender, date, next EMI, due date. More in our payment confirmation message templates.
EMI bounce message format
16. Bounce, same day
Dear {{1}}, your EMI of {{2}} for loan ending {{3}} with {{4}} could not be collected on {{5}} (bank reason: {{6}}). A bounce charge of {{7}} applies per your agreement. Pay here: {{8}}. Facing difficulty? Reply HELP to discuss options.
Key: name, EMI, last four digits, lender, date, reason, charge, pay link.
17. Bounce follow-up
Get a 1-minute BSP audit on WhatsApp
Drop your WhatsApp number — we line-item your current invoice against Meta India rates in under 60 seconds. India-hosted, DPDP-compliant.
Hi {{1}}, a gentle follow-up from {{2}}: the EMI for loan ending {{3}} is pending. Total due with charges: {{4}}. Pay here: {{5}}. Already paid? Please ignore this. To agree a date, reply TALK.
Key: name, lender, last four digits, total due, pay link.
18. Final grace-period notice
Dear {{1}}, notice from {{2}}: the EMI of {{3}} for loan ending {{4}} is unpaid. Paying by {{5}} avoids further late charges under your agreement. Pay here: {{6}}. For a concern, contact our grievance officer at {{7}}. Thank you.
Key: name, lender, EMI, last four digits, grace date, pay link, grievance contact.
Loan rejection message
19. Application declined
Dear {{1}}, thank you for applying to {{2}}. We are unable to approve application {{3}} at this time. Main reason: {{4}}. You may reapply later. Grievance officer: {{5}}. Thank you.
Key: name, lender, application ID, reason category, grievance contact.
20. Application closed (incomplete)
Hello {{1}}, application {{2}} with {{3}} is closed because {{4}}. No charges were applied. Start a new application any time: {{5}}. Grievance officer: {{6}}. Thank you.
Key: name, application ID, lender, reason, application link, grievance contact.
Loan closure / NOC issued
21. Loan closed, NOC attached
Dear {{1}}, your loan ending {{2}} with {{3}} is fully repaid and closed as of {{4}}. Your No-Dues Certificate is attached, and we have requested cancellation of the linked e-mandate.
Key: name, last four digits, lender, closure date; PDF header.
22. Documents ready
Hello {{1}}, original documents for closed loan ending {{2}} with {{3}} are ready at {{4}} from {{5}}. Please bring photo ID.
Key: name, last four digits, lender, branch, date.
Template variable map
Blank amount, date or ID? Hold the send.
| Variable | What it holds | Example value | Source system |
|---|---|---|---|
| Borrower name | First name from KYC | Fallback “Customer” | LOS |
| Loan ID | Borrower-facing reference | LN-20418 | LOS / LMS |
| Lender | Regulated entity | Sample Finance Ltd | LOS |
| Amount | Sanctioned principal | ₹2,50,000 | LOS |
| Rate / APR | Interest and all-in APR | 13.5% p.a. / 14.9% | LOS |
| Tenure | Repayment period | 24 months | LOS |
| EMI | Instalment and start date | ₹11,944 from 5 Nov 2026 | LMS |
| Account ending | Last four digits | 4821 | Core banking |
| Bounce reason | Bank return reason | Insufficient balance | E-mandate / NACH provider |
| Pay link | Loan-specific pay page | [lender-domain]/pay/LN-20418 | Payment gateway |
RBI-aligned rules for loan messages on WhatsApp
This is not legal advice. Check the current RBI master direction with your compliance team.
| Rule | What it means for the message | Example wording |
|---|---|---|
| KFS before execution | Link the KFS (APR, fees, cooling-off period) before acceptance | “Please review your Key Fact Statement before you sign.” |
| Cooling-off / look-up period | Point to the exit window stated in the KFS | “Your KFS explains the cooling-off period.” |
| Regulated lender named | Name the regulated entity; an LSP must not pose as the lender | “Your lender is Sample Finance Ltd.” |
| Grievance officer | Give the grievance route on credit and recovery messages | “Unresolved? Escalate under the RBI Integrated Ombudsman Scheme.” |
| Fair recovery conduct | No threats, shaming or contacting references; permitted hours only (commonly cited as 8am–7pm, verify) | “Facing difficulty? Reply HELP.” |
| Consent (DPDP) | Timestamped, revocable opt-in; honour opt-outs instantly | “Reply STOP to opt out.” |
Utility vs Marketing: the call that sets your price
On WhatsApp, a sanction or disbursal notice is a Utility template; a pre-approved top-up offer is a Marketing template. Sanction, disbursal, EMI and NOC messages update a loan that is already in progress. Top-ups and cross-sell promote something new, which moves the cost from ₹0.115 to ₹0.8631 per message (BSP-reported). Meta categorises templates by content, not intent, so a single upsell line can flip one. More in WhatsApp template categories.
- Add realistic sample values (₹2,50,000, 24 months).
- Never start or end the body with a variable.
- Attach the sanction letter or KFS as a PDF document header.
- Add quick replies “Accept offer” and “Talk to an officer”. Route “Accept offer” to your KFS acceptance flow, not a signature.
Rejected? Our guide to template rejection reasons and fixes maps each label to a fix.
What loan-lifecycle messages cost on WhatsApp
These costs use the ₹0.115 utility rate per delivered message and exclude 18% GST. Meta revises rates, so confirm the live rate card.
| Messages a month | Meta utility cost | Client Pay (Meta + ₹0.10) | SaaS Pay (₹0.50 each) |
|---|---|---|---|
| 10,000 | 10,000 × ₹0.115 = ₹1,150 | ₹1,150 + ₹1,000 = ₹2,150 | 10,000 × ₹0.50 = ₹5,000 |
| 50,000 | 50,000 × ₹0.115 = ₹5,750 | ₹5,750 + ₹5,000 = ₹10,750 | 50,000 × ₹0.50 = ₹25,000 |
| 2,00,000 | 2,00,000 × ₹0.115 = ₹23,000 | ₹23,000 + ₹20,000 = ₹43,000 | 2,00,000 × ₹0.50 = ₹1,00,000 |
If the same 10,000 messages were Marketing, Meta alone would charge 10,000 × ₹0.8631 = ₹8,631. From 1 October 2026, Meta charges for service messages (free-form replies inside the 24-hour window) and for utility templates sent inside that window, billed per delivered message at the utility rate: ₹0.115 plus 18% GST in India. BSPs report that the first 1,000 service messages per number each month stay free, but that covers free-form replies, not utility templates. See the October 2026 WhatsApp price change. RichAutomate plans are Starter ₹499/mo, Pro ₹899/mo and White-label ₹1,199/mo.
How to automate loan messages without code
- Status change triggers the send: the LOS/LMS fires a webhook; verify it, acknowledge fast and queue the matching template.
- Map variables from the loan record: cosmetic fields get a fallback; a missing transactional field holds the send.
- Bounce file to bounce template: a NACH return file triggers template 16, sent in permitted hours only.
- Dedupe on loan ID + stage so a borrower never gets two approvals.
- Escalate replies to a human officer: the platform is the messenger, not the lender.
Mistakes to avoid
- Approval sent before the credit decision is final (use template 7).
- No APR or KFS link.
- Threatening bounce wording, such as “legal action today”.
- A top-up upsell inside a Utility template.
- Late-night or early-morning sends.
- No timestamped opt-in record.
Ready to test your first sanction template? Start a 14-day free trial with 100 free credits on RichAutomate, with ₹0 setup and ₹0 monthly on usage-only billing. Meta reviews every template, so approval is never assured.
Frequently asked questions
What is the format of a loan approval message?
Start with the borrower’s name. Then give the loan type, approved amount, rate and APR, tenure, EMI and first-EMI date, and processing fee. Add the KFS link, the next step, how long the offer is valid, the lender name and a grievance contact.
Is a loan approval message a Utility or Marketing template on WhatsApp?
It is Utility, because it updates an application the borrower started. Pre-approved, top-up and cross-sell offers are Marketing. The BSP-reported rates are about ₹0.115 versus ₹0.8631; confirm the live rate card.
How should an EMI bounce message be worded?
Keep it polite and factual. Give the EMI, a masked loan reference, the date, the bank’s reason, the agreed charge, a payment link and a help option. Never threaten, and send only in permitted hours.
What should a loan rejection message say?
Thank the applicant, state that the loan was not approved and give the reason category. Confirm they can reapply, and share the grievance officer contact.
Can I send a loan disbursement message without a template?
Only as a free-form reply inside an open 24-hour window. From 1 October 2026 those replies are charged beyond the free allowance BSPs report. Outside the window, use an approved Utility template.